News
New Wheelchair and Rollator Billing Codes Reshape Export Line-Ups
A law signed in Washington on 10 November 2026 has handed the walking aid trade a new sorting rule. From 2028, Medicare will pay for ultralightweight manual wheelchair bases through separate billing codes depending on whether the frame uses titanium or carbon fibre, and suppliers may bill the patient for the difference if the extra cost is disclosed first. The Choices for Increased Mobility Act became Public Law 119-140 after passing both chambers by voice vote, less than a fortnight after eight product codes, that same wheelchair base among them, joined Medicare's prior authorisation list on 28 October. In a mobility aids market projected to grow from USD 2.95 billion in 2026 to USD 5.50 billion by 2035, the specification that wins is increasingly the one a payer recognises.
The demand behind those figures is not in dispute. Rollators took 43.28% of walking aid revenue in 2025, home care settings 44.3% and North America 36.42%, while Asia-Pacific compounds near 7.1% a year. Aluminium still holds 56.9% of frame material revenue, with carbon fibre the fastest-growing input, so the material question now carries a payment consequence that travels back up the supply chain to Guangdong. The same research puts China's walker revenue on an 8.3% annual path to 2036, the fastest of ten major markets, against 5.3% in the United States.
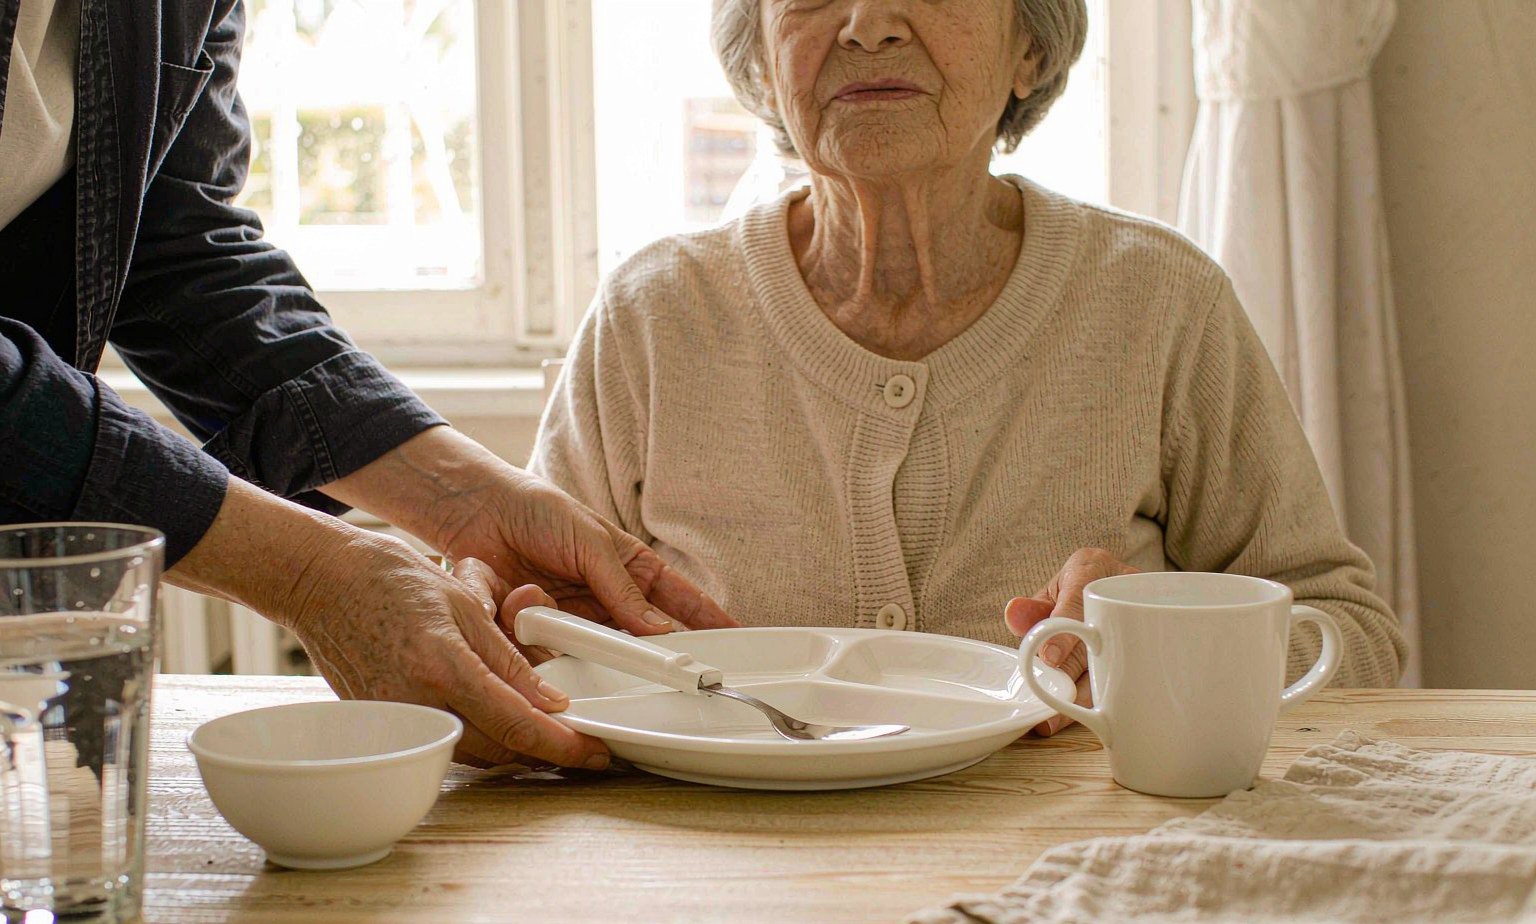
Walk through a house and the coding logic stops at the front door. A shower chair, a suction grab bar or a non-slip bath mat usually sits outside any reimbursement route, so the purchase is settled by fit, weight and how it looks in a bathroom. Much the same applies to a bed rail, an adjustable bed or a pressure relief mattress in the bedroom, and to adaptive utensils, a non-slip plate and a two-handled cup at the table. Margin in these lines comes from packaging, instruction clarity and the returns rate. Even where a walking frame or rollator does move through insurance, the sale is a paperwork exercise: Ontario's Assistive Devices Program funds 75% of an approved price through registered vendors, and Australia's Support at Home scheme puts assistive devices inside a separately assessed budget.
The costliest errors sit on the boundary between two categories. A four-wheeled walker with a resting seat and a device that also functions as a transport chair can be classified differently, and since October 2026 CMS treats the combination product under its own code as durable medical equipment while still applying the walker and transport-chair criteria. The Netherlands shows the other extreme: simple walking aids including rollators and walking frames are not reimbursed from the basic package, leaving buyers to choose between a lightweight folding rollator on price and a premium model on specification. Germany's insurers sit in between, with features beyond the necessary level leaving the user to pay the gap. A supplier who cannot state on one page which function is being billed hands the order to a competitor who can.
For importers the consequences run through the order sheet. Frame alloy, base weight, whether a seat is rated for resting or sitting, brake type and the accessory list now need documenting at SKU level, because one option can shift a product into a different billing category and change the landed cost. Expect fewer bundled kits and more separate line items, more demands for spare parts and warranty commitments, and closer reading of instructions for use, since a patient billed for an upgrade has to understand what the upgrade does. The Dutch arrangements that wrap service and parts around a frame are the model buyers now quote.
Two judgements follow. The walking aid range is splitting into two businesses sharing one factory but not one channel: coded volume lines, where a fee schedule dictates the specification and price pressure never lifts, and self-pay lines such as grab bars, lift chairs, riser recliners, pressure relief cushions, reacher grabbers and pill organizers, where design, retail packaging and a coherent price ladder decide the outcome. The shift also suits Chinese manufacturers, whose weakness has been volume without value: manual wheelchair export units kept rising while export value stayed flat and average prices fell more than a fifth over five years. Guangdong already holds 50 to 60% of domestic wheelchair and walker share and roughly 70% of national exports in these lines. A rule that pays separately for a titanium or carbon base, and lets the supplier bill the difference, rewards exactly the finishing work that a low-price strategy cannot monetise.
The quieter shift sits where no code exists at all. Fall detection radar, an emergency call button, a smart mattress and remote patient monitoring are bought by families and home care operators on trust and price rather than reimbursement, and the same is true of a mobility scooter or a quad cane chosen privately for the street. That makes the silver economy a retail market as much as a medical one, and it explains why buyers increasingly want one supplier who can cover a bathroom, a bedroom and a dining table. Independent living is assembled from small purchases, and the supplier that makes those easy to combine takes the repeat order.
Yiwu Orange Light Future Technology keeps a close eye on global trends in elderly health. Specializing in age-friendly wellness products, we offer a range of mature solutions to support seniors' safety and health at home. We welcome inquiries and business discussions from all partners!
RELATED NEWS
- UN Decade of Healthy Ageing Mid-Term Action: Global Nations Sign Framework to Re
- Silver Tourism Nears $2T: Healthy Travel Drives Core Growth
- Transformation of Walking Aids: Three Innovations — Lightweight, Smart, Human-Or
- International Elderly Care Guide: Guidelines for Proper Commode Chair Use Releas
- More Than Barrier-Free: Health Evaluations Join Public Transport Services for th
CATEGORIES
LATEST NEWS
CONTACT US
Name: Fannie
Mobile:+86 13375799060
Tel:+86 13375799060
Whatsapp:+86 13375799060
Email:fannie@ywolftech.com
Add:589 Longtan Road,Jinhua City Zhejiang Province China